The real cost of owning a car in Malaysia
MoneyMama · 13 July 2026 · 7 min read
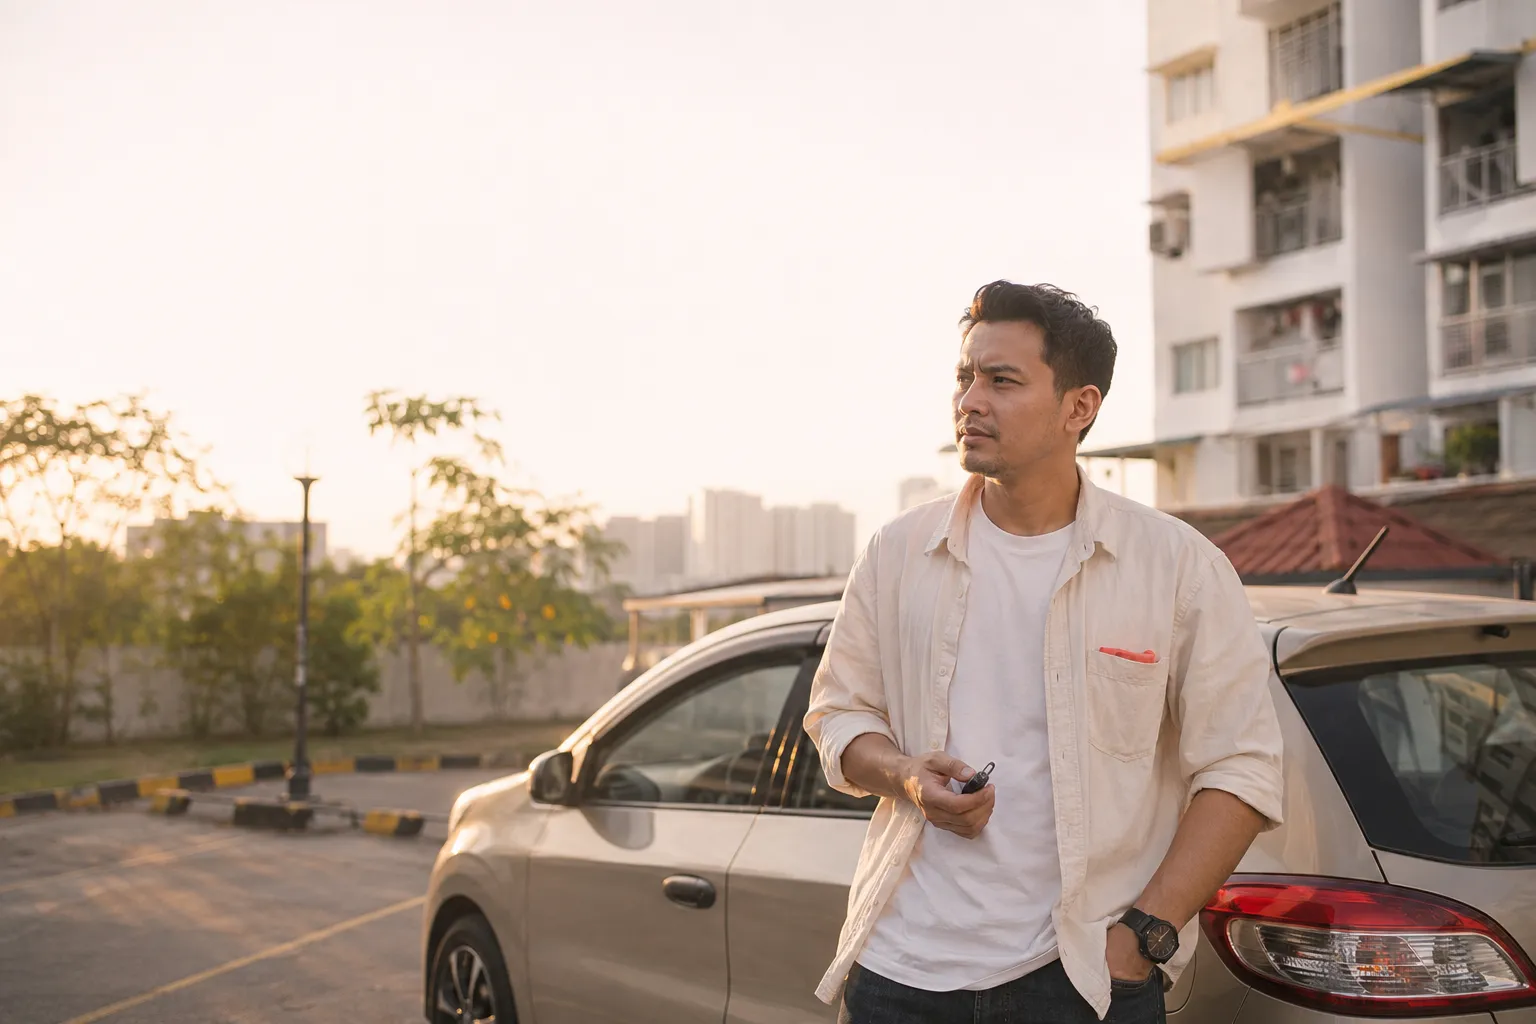
We’re told a nicer ride means you’ve made it. Bigger badge, newer plate, and suddenly people assume you’re doing well. But here’s the quiet thing a lot of Malaysians live with: the car loan is often the exact reason they feel stressed every single month. Nobody sees the potong gaji, they just see the car.
This isn’t a lecture about giving up your wheels. We know Malaysia is built for cars and sometimes you really do need one. It’s just the honest maths on what a car actually costs, and how much car your salary can carry without squeezing everything else flat.
Here is the short version. Keep your car installment under 10% of your take-home pay, and all your loans together (car plus house) under 30%. A car that shows RM1,000 on the installment really costs closer to RM1,500 a month once you add petrol, tolls, parking, insurance and maintenance. So on a RM10,000 take-home income, the car you can comfortably afford is a new Myvi, not a Honda. And never sign a 9-year loan: if you need nine years to afford it, that’s the car telling you that you can’t.
The 10% rule (and the 30% ceiling)
The number to hold onto is simple. Your car installment should stay under 10% of your take-home pay, and every loan you carry together (car plus house) should stay under 30%.
Say your take-home is RM10,000. That points you at roughly a RM1,000 installment. Sounds fine, until you remember the installment is only the entry fee. Car insurance alone is another 10% to 15% of your installment amount each year, and even with a full 50% no-claim bonus a Myvi still runs you around RM700 a year. The financial-education channel Mr Money TV walked through this exact maths, and it’s worth 20 minutes if cars are on your mind:
Why a RM1,000 car really costs RM1,500
Here’s the part most people forget to count. On top of the installment, you’re paying petrol (roughly RM200 to RM300 a month), tolls, parking (RM200 to RM300 a month if you’re in KL), insurance and maintenance. Add it up and you’re looking at 30% to 50% on top of the sticker installment.
So a “RM1,000 car” is really a RM1,500 car. On a RM10,000 take-home income that’s still workable: RM1,500 for the car, RM2,000 saved (a healthy 20%), maybe RM2,000 on food if you’re eating properly in KL, and you’re left comfortable. But the moment you add rent of RM1,500 to RM2,000, or start thinking about a house, that breathing room disappears fast.
The trick is to actually see your full car cost in one place, not scattered across petrol receipts and Touch ‘n Go top-ups. That’s the everyday job MoneyMama does in WhatsApp:
What your salary can actually afford
Once you apply the 10% rule, the ladder is clearer than most people expect.
At RM10,000 take-home, RM1,000 buys you a top-spec new Myvi (about RM60,000 with a small down payment). At RM20,000 you’re into Honda Accord or BYD Seal money. At RM50,000, a BMW 5 Series. And the humble Myvi is now a RM60,000 car, which quietly makes it a rich man’s ride. If a household earning RM10,000 should be driving a Myvi, then “10k a month” is not as much as it feels.
This is where fresh grads get squeezed. Many start around RM2,500 to RM3,000, and Malaysia’s minimum wage sits at RM1,700 a month. Under a strict 10% rule, a brand-new car is simply out of reach. The realistic answer isn’t “no car”, it’s a used car: a 5 to 7-year-old Axia around RM23,000 works out to roughly RM300 to RM400 a month. Not syok, but honest. A second quick sanity check the video offers: your car’s price shouldn’t be more than one year of your salary. Earn RM3,000 a month? Keep the car under RM36,000.
The 9-year loan trap
Stretching the loan to nine years is how people fool themselves into a car they can’t afford. Here’s why it kena you. Most cars are under warranty for about five years, and by year eight or nine the car has fully depreciated, yet you’re still paying the bank. Worse, if you try to sell, the market price is often lower than what you still owe, so you’d have to top up cash just to get out of the loan. You’re trapped in a car that’s giving you problems, with no room to change.
The rule of thumb: seven years, maximum. If the only way the sums work is a 9-year loan, that’s your signal to look one tier cheaper.
Car or house: you often can’t have both
This is the trade-off nobody likes to say out loud. With a 30% total-loan ceiling, if the car eats 20% or more, the house gets pushed years down the road. Every extra ringgit on the car is a ringgit that isn’t building your emergency fund or your house down payment. Start from zero, overspend on the car, and you’re simply choosing car now, house later. That’s not wrong, it just needs to be a choice you made on purpose, not one the salesperson made for you.
The car isn’t impressing anyone anymore
There’s a real social pressure here, especially on guys, and it’s fair to name it. But the maths of showing off has changed. In KL, most people’s families already own that “nice” car, or their friends do. You can’t really impress anyone with a badge now; you’d have to go full Bentley, and that’s a different kind of trouble.
A car is a liability that depreciates, not an asset that pays you back. As one point in the video put it, money is just a tool to make you happy, so if a car genuinely makes you happy, go for it, but only once you can afford it without skipping meals or coffees with friends. If you actually want to prove you’re doing well, a healthy bank balance says it louder than any plate.
Know your number before you sign
Before you fall in love with a car, do the boring five minutes: work out your real take-home, your 10% installment cap, and the full RM1,500-not-RM1,000 monthly cost. MoneyMama can carry that for you, logging every petrol, parking and toll ringgit in the WhatsApp chat you already use, so your true car cost is never a month-end shock.
Say hi to MoneyMama on WhatsApp and start tracking what your car really costs, one message at a time. Then you can buy the car you like because you can afford it, not because everyone else expected it.